What Is a Robo-Advisor? How Automated Investing Works
A robo-advisor is a digital platform that builds and manages your portfolio automatically. Learn how it works, what it costs, and who it’s for.
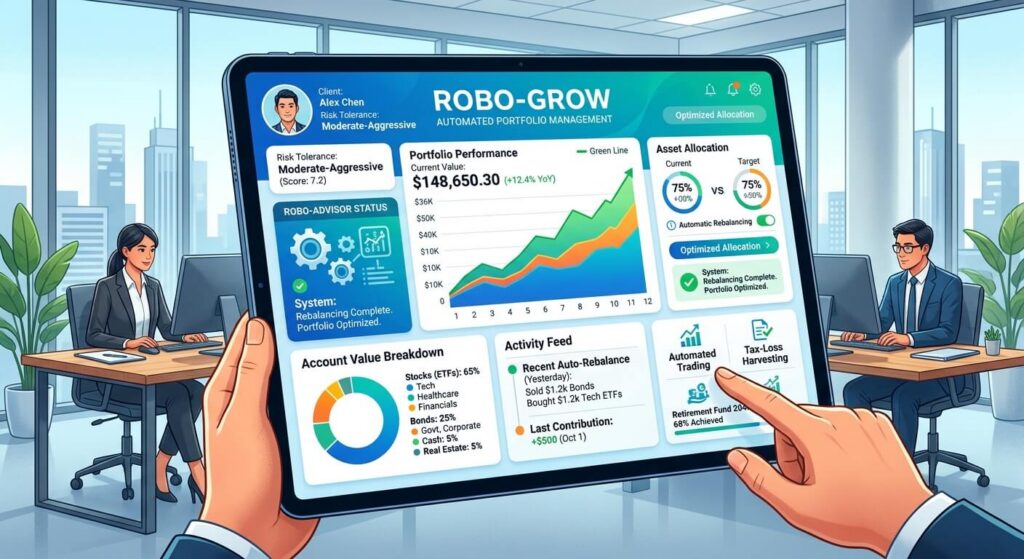
A robo-advisor is a digital platform that builds, manages, and rebalances an investment portfolio on a client’s behalf using computer algorithms rather than a human portfolio manager. Investors answer a short questionnaire about their goals, time horizon, and risk tolerance, and the platform allocates their money — typically across low-cost exchange-traded funds (ETFs) — and adjusts that allocation automatically over time. In the United States, robo-advisors are regulated as registered investment advisers and are legally bound by the same fiduciary duty as traditional financial advisors.
Key Facts
- The first robo-advisory platforms appeared in 2008, and Betterment launched its digital portfolio-management interface in 2010, generally credited as the product that popularized the category.
- Robo-advisors are registered with the U.S. Securities and Exchange Commission (SEC) or state regulators and are subject to the Investment Advisers Act of 1940, including its fiduciary standard.
- Annual management fees among major U.S. providers typically range from 0% to roughly 0.25%–0.65% of assets under management, though “no-fee” models can carry indirect costs.
- Common features include automatic portfolio rebalancing, dividend reinvestment, and — on several platforms — tax-loss harvesting.
- In the European Union, robo-advisory services operate under the MiFID II framework, which governs suitability assessments and cost disclosure for automated investment advice.
How a Robo-Advisor Works
Signing up for a robo-advisor generally starts with an online questionnaire covering an investor’s goals, investment timeline, income, and comfort with market volatility — questions such as what the money is for, when it will be needed, and how the investor would react to a sharp short-term loss. The platform uses those answers to assign a portfolio, usually a mix of stock and bond ETFs calibrated to the investor’s risk profile, and to determine both the asset allocation and the specific funds used to fill it.
From there, the platform operates with limited human intervention. It monitors the portfolio and automatically rebalances it — buying and selling assets to bring the allocation back to its target — when market movements push it off course. Many platforms also reinvest dividends automatically rather than leaving them as idle cash.
A subset of robo-advisors, including Betterment and Wealthfront, additionally offer tax-loss harvesting: a strategy that sells positions trading at a loss to offset realized capital gains elsewhere in the portfolio, reducing an investor’s tax bill. Some platforms extend this further with direct indexing, which holds individual stocks that replicate an index rather than a fund, allowing for more granular tax-loss harvesting at higher account balances.
Some robo-advisors are pure digital products; others are “hybrid” models that pair the algorithm with access to human financial planners, usually for an additional fee.
Regulation: Who Oversees Robo-Advisors
In the U.S., robo-advisors are not a separate legal category — they are registered investment advisers (RIAs) that deliver advice primarily or entirely through a website or app. That means they fall under the SEC’s Investment Advisers Act of 1940 and owe clients the same fiduciary duty as a traditional human advisor: an obligation to act in the client’s best interest. The SEC has published specific guidance for the sector, noting that robo-advisers must meet disclosure, suitability, and compliance obligations, even though the way they satisfy those obligations — through automated onboarding rather than an in-person meeting, for example — differs from a conventional advisory relationship.
Advisers generally register with the SEC once they cross $100 million in assets under management, though a separate “internet adviser exemption” allows qualifying digital-only advisers to register with the SEC below that threshold. The SEC tightened that exemption in 2024, requiring firms to deliver advice exclusively through an interactive website to keep qualifying, with firms that no longer met the criteria required to transition to state-level registration by mid-2025.
Outside the U.S., regulatory frameworks differ. In the European Union, robo-advisors operate under MiFID II, which sets baseline requirements for how client information is collected, how portfolio suitability is assessed, and how costs are disclosed to investors.
What a Robo-Advisor Costs
Fee structures vary by provider, and the “lowest headline fee” isn’t always the lowest real cost. Based on current provider disclosures:
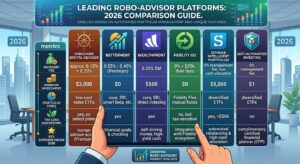
| Provider | Advisory Fee | Account Minimum | Notable Feature |
|---|---|---|---|
| Betterment | 0.25%/year (or $5/month on lower balances) | $0 | Tax-loss harvesting on taxable accounts; optional CFP access at a higher tier |
| Wealthfront | 0.25%/year | $500 | Direct indexing and stock-level tax-loss harvesting at $100,000+ |
| Schwab Intelligent Portfolios | 0% stated management fee | $5,000 | No advisory fee, but requires a mandatory cash allocation (roughly 6%–10% of the portfolio, higher for conservative profiles) held at Schwab Bank |
| Fidelity Go | 0% under $25,000; tiered above that | $0 | Uses Fidelity’s own zero-expense-ratio index funds at the lowest tier |
Investors should treat headline management fees as only part of the picture. Underlying fund expense ratios apply on top of any advisory fee, and “zero-fee” models that rely on a mandatory cash allocation can create what industry commentary calls “cash drag” — the opportunity cost of holding a portion of the portfolio in cash earning a bank sweep rate rather than being invested in the market. Whether that trade-off costs more or less than an explicit 0.25% fee depends on prevailing interest rates and the size of the required cash allocation.
Who Uses a Robo-Advisor
Robo-advisors are commonly positioned toward investors who want diversified, professionally structured portfolios without the higher account minimums and higher fees historically associated with human financial advisors. In practice, that includes:
- First-time investors looking for a low-minimum, low-effort way to start investing rather than picking individual securities.
- Retirement savers, including those using robo-advisors inside an IRA or Roth IRA, where automated contributions and rebalancing can simplify long-term, tax-advantaged saving.
- Investors who want a “set it and forget it” approach, rather than actively managing allocations themselves.
- Cost-conscious investors comparing automated management against the higher percentage fees typically charged by traditional human advisors.
Robo-advisors are generally less suited to investors with complex financial situations — significant equity compensation, business ownership, or estate-planning needs — where nuanced, individualized advice from a human planner may be more appropriate. Several providers address this gap through hybrid tiers that add access to a certified financial planner for an additional fee.
Risks and Limitations
Balanced against the convenience, several limitations are worth flagging:
- Algorithms rely on historical data and models, which have inherent limits in forecasting future market behavior — a limitation shared with most quantitative investment approaches, not unique to robo-advisors.
- Portfolios are generally standardized around a small number of risk profiles, which may not capture an individual investor’s full financial picture.
- “Zero-fee” models can carry indirect costs, such as the cash-allocation drag described above, that are less visible than an explicit percentage fee.
- Automated advice does not replace professional guidance for tax, legal, or estate-planning questions, and using a robo-advisor does not eliminate investment risk, including the potential loss of principal.
- Regulatory obligations continue to evolve. The SEC’s 2024 tightening of the internet adviser exemption illustrates that the compliance framework around digital advice is still being refined, which can affect how some platforms operate over time.
Robo-Advisors vs. Traditional Financial Advisors
The core distinction is delivery method and cost structure, not necessarily portfolio sophistication. Traditional human advisors typically charge a higher percentage of assets under management and may offer more comprehensive financial planning — tax strategy, estate planning, insurance review — alongside investment management. Robo-advisors generally charge less, require lower or no account minimums, and focus narrowly on portfolio construction and maintenance, with human planning available only through hybrid tiers on some platforms. Neither model is inherently superior; the appropriate choice depends on the complexity of an investor’s financial situation and their preference for human interaction.
Frequently Asked Questions
Is a robo-advisor a fiduciary? In the U.S., robo-advisors that are registered investment advisers are legally required to act as fiduciaries under the Investment Advisers Act of 1940, meaning they must act in the client’s best interest, the same standard that applies to traditional human RIAs.
How much money do you need to start using a robo-advisor? It varies by provider. Some platforms, including Betterment and Fidelity Go, have no required minimum, while others, such as Wealthfront and Schwab Intelligent Portfolios, require a minimum initial deposit, generally in the $500–$5,000 range.
Can a robo-advisor lose money? Yes. A robo-advisor manages a portfolio of market-linked assets, typically ETFs, and those assets can decline in value. Automation does not eliminate market risk or guarantee a return.
Do robo-advisors work for retirement accounts like a Roth IRA? Most major robo-advisors support IRAs and Roth IRAs, applying the same automated allocation and rebalancing approach within the tax rules that govern those account types.
What’s the difference between a robo-advisor and a self-directed brokerage account? A self-directed account requires the investor to select and manage individual holdings themselves. A robo-advisor automates that selection and ongoing management based on the investor’s stated goals and risk tolerance.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or legal advice. Global Crypto 360 does not endorse any specific asset, platform, or strategy mentioned. Always conduct your own research (DYOR) and consult a licensed financial professional before making financial decisions.